Advice Business Tax

GST for Allied Health Practices: What’s GST-Free and What Isn’t

Ask most allied health practitioners about GST and you’ll hear the same thing: “Health is GST-free, so I don’t need to worry about it.” That’s half right. And the other half is where the ATO finds money.

Here’s what GST for allied health actually looks like, what’s GST-free, what isn’t, and the registration trap that catches growing practices.

When a health service is GST-free

A health service is generally GST-free when all three of these are true:

  1. It’s a service in a recognised health profession listed in the GST law. That includes physiotherapy, psychology, occupational therapy, podiatry, dietetics, speech pathology, chiropractic, osteopathy, optometry and audiology, among others.
  2. It’s provided by someone who is registered or accredited in that profession.
  3. It’s generally accepted in that profession as necessary for the appropriate treatment of the patient.

Your standard consult, assessment and treatment session usually ticks all three. Telehealth sessions work the same way.

What usually isn’t GST-free

This is where practices get caught out:

  • Products you sell, like supplements, braces, tape, rollers or skincare, are often taxable
  • Cosmetic services that aren’t medically necessary
  • Room hire or service fees you charge to contractors working in your clinic
  • Reports for legal or insurance purposes rather than treatment
  • Corporate workshops and wellness programs sold to employers that aren’t treatment for an individual patient
  • Training, supervision or courses you deliver to other practitioners

NDIS supports have their own GST-free rules, with specific conditions around the participant’s plan and a written agreement. Don’t assume they fit the same box as your private patients.

GST for allied health: the registration trap

You must register for GST once your GST turnover hits $75,000 a year. Here’s the kicker: GST-free sales count towards that turnover.

So a physio billing $180,000 a year in GST-free treatments, plus $8,000 in product sales, is over the threshold. They need to be registered and charging GST on those products, even though most of their income is GST-free.

Being registered isn’t all bad news. You can claim GST credits on business purchases like equipment, fit-out and software.

Running a clinic with contractors?

If you take a percentage of a contractor’s billings as a service fee, that fee is usually a taxable supply from you to them. It isn’t GST-free just because the patient’s treatment is.

Get this wrong across a few years and you could owe GST you never collected. This often pops up alongside payroll tax questions, so it’s worth reviewing both together.

GST for allied health: a quick check for your practice

  • List everything you charge for, not just consults
  • Mark which items are treatment and which are products or business services
  • Check your GST turnover against the $75,000 threshold (including GST-free income)
  • Make sure your practice software is coding items correctly
  • Review your contractor service fee arrangements

The honest bit

“Health is GST-free” is a nice simple rule that isn’t actually true. Most of what you do probably is GST-free. The bits around the edges are where the risk sits, and they grow as your practice grows.

We look after allied health practices across Brisbane and Queensland. If you want someone to check your GST setup properly, book a chat with us.

Related reading:

This article is general information only and isn’t personal advice. GST outcomes depend on the specific service, so please get advice before acting.
Advice Business Tax

Division 7A Explained: Taking Money Out of Your Company Without an ATO Headache

Here’s a Division 7A conversation we have a lot. A business owner runs their trade or practice through a company. The company account is healthy. They need money for the mortgage, a car or a family holiday, so they transfer it across. It’s their business, so it’s their money, right?

Not quite. Once you set up a company, the company’s money belongs to the company. Take it out the wrong way and Division 7A can treat it as an unfranked dividend, taxed at your marginal rate with no franking credits to soften the blow.

What Division 7A actually is

Division 7A is a set of tax rules that stop private company profits reaching shareholders (and their family members or related entities) tax-free. It catches three main things:

  • Loans from the company to you, your spouse, your family trust or another associate
  • Payments to you or your associates, including the company paying your personal bills
  • Debts forgiven by the company

It can also catch private use of company assets, like a holiday house or boat the company owns that the family uses for free.

How it sneaks up on people

Most Division 7A problems start small. The company pays your personal credit card. You take $5,000 here and $10,000 there. Nobody records it as salary or a dividend, so at year end it sits in the books as a “loan to director.”

That balance is now a Division 7A loan, and the clock is ticking.

The deadline that matters: lodgment day

You have until the company’s tax return is due (or lodged, if earlier) to sort it out. By then, the loan must either be:

  • repaid in full, or
  • put under a complying loan agreement

Miss that and the whole amount can be treated as a deemed dividend.

What a complying Division 7A loan looks like

A complying Division 7A loan needs to be:

  • in writing, signed before lodgment day
  • charging interest at least equal to the benchmark rate, which is 8.77% for 2026-27 (it was 8.37% in 2025-26)
  • for a maximum term of 7 years unsecured, or 25 years if secured by a registered mortgage over real property

Then you need to make a minimum yearly repayment by 30 June every year. As a rough guide, a $100,000 seven-year loan needs about $20,000 a year in repayments. Fall short and the shortfall can be treated as a dividend.

The interest you pay is income to the company, so it gets taxed there too. Division 7A loans are a tool for managing timing, not a free lunch.

Ways to clear a Division 7A loan

The good news is there are usually tidy ways to deal with it:

  1. Declare a dividend and offset it against the loan. You get franking credits for tax the company has already paid.
  2. Pay yourself a wage or director’s fee and use it to repay the loan. This brings PAYG and super into play, so plan it.
  3. Repay it with personal funds if you have them.
  4. Put a complying loan in place and repay it over time.

Which one is right depends on your marginal tax rate, the company’s franking account and your cash flow. This is exactly the kind of thing worth modelling before 30 June, not after.

Stop it happening again

  • Keep business and personal spending on separate cards
  • Pay yourself a regular wage or set drawings plan we agree on up front
  • Review your director loan account every quarter, not once a year
  • Ask before using company money for anything personal, even “just this once”

The honest bit

Division 7A is one of those rules nobody tells you about when you set up a company, and then everyone acts surprised when it bites. It’s fixable, but it’s much cheaper to fix early.

If your company account has been doubling as your personal account, we won’t judge, we’ll just help you clean it up. Book a time with us and we’ll take a look at your director loan.

Related reading:

This article is general information only and isn’t personal advice. Please get advice on your own situation before acting.

Advice Tax

Tradie Tax Deductions in Brisbane: What You Can Actually Claim

When it comes to tradie tax deductions, every tradie has a mate at the pub who “claims everything.” That mate is usually one audit away from a very bad year.

The truth is, most tradies in Brisbane are under-claiming the things they’re entitled to and over-claiming the things that get flagged. This guide covers the tradie tax deductions that matter, where people trip up, and what records you actually need.

Tradie tax deductions for tools and equipment

Tools you use to earn your income are deductible. How you claim them depends on cost and whether you’re running a business.

  • Running your own business (sole trader, company or trust) with turnover under $10 million: the instant asset write-off lets you deduct the full cost of an eligible asset under $20,000 in the year it’s first used or installed ready for use. The limit is per asset, so two $12,000 items can both be written off.
  • Assets $20,000 or more go into the small business depreciation pool instead.
  • Working as an employee: tools under $300 can usually be claimed in full straight away. Over $300, you depreciate them over their effective life.

One thing to watch: the $20,000 limit is tested on the full cost of the asset, not just your business-use portion. A $25,000 item used 60% for work still goes in the pool.

The Federal Government announced in the May 2026 Budget that the $20,000 limit would become permanent from 1 July 2026. Check with us before you make a big purchase so you know exactly which limit applies to you.

The ute (and why it’s different from a car)

This is where tradies either save a lot or get burnt.

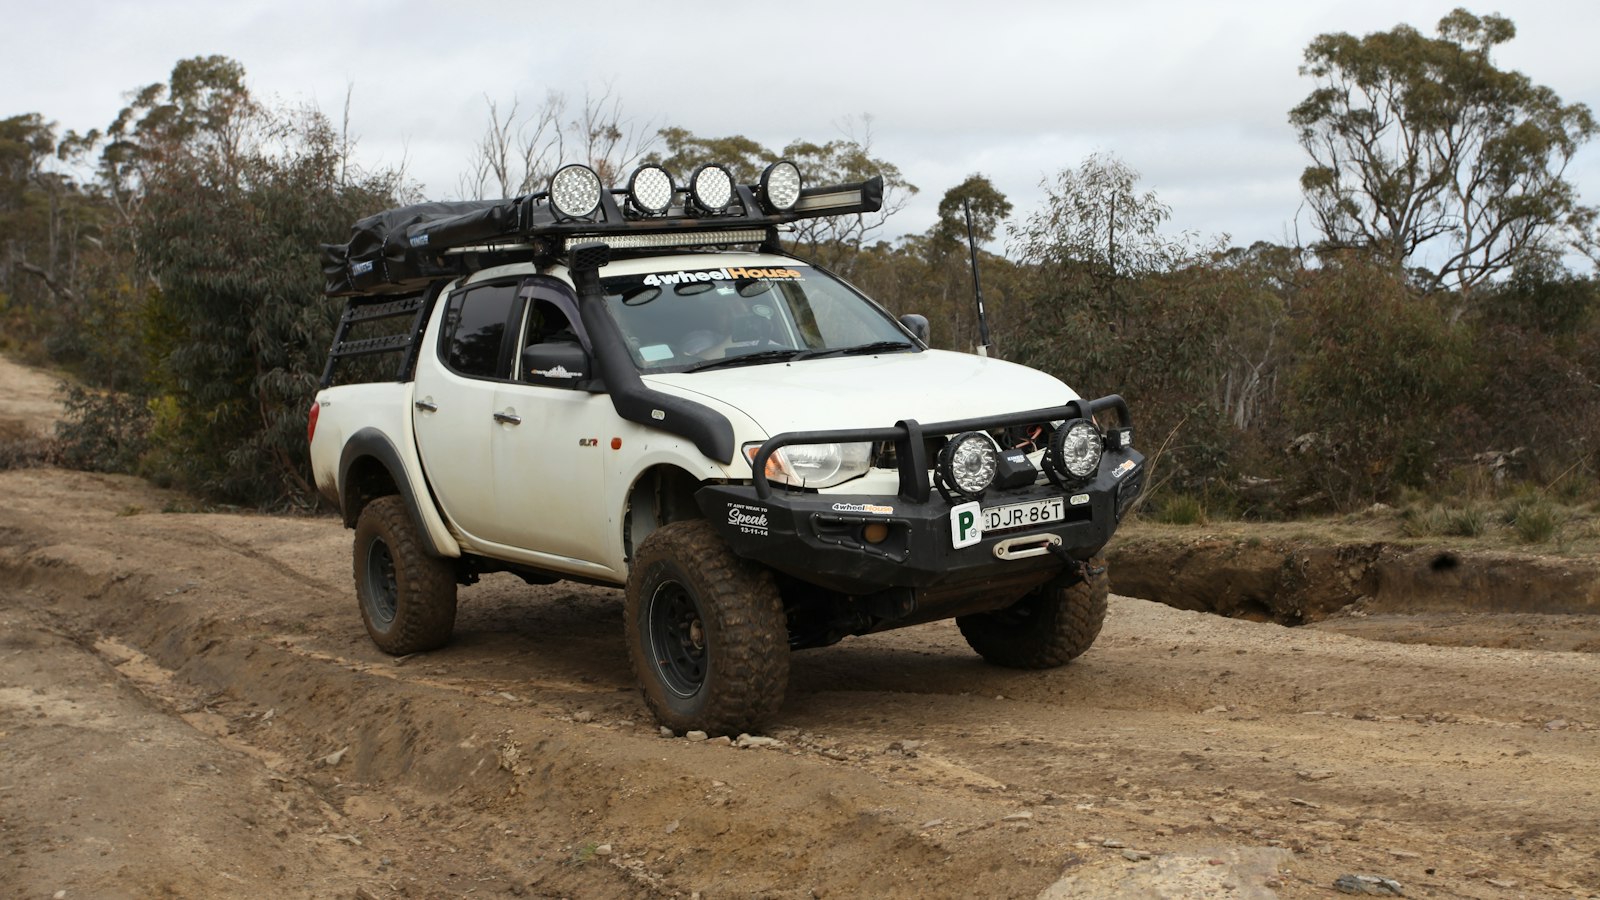
If your ute is designed to carry one tonne or more, or nine or more passengers, the ATO doesn’t treat it as a “car.” That means:

  • the car limit doesn’t cap your depreciation
  • you don’t use the logbook or cents per kilometre methods
  • you claim the actual costs (fuel, rego, insurance, servicing, depreciation, interest) for the work-use portion

Sounds great. The catch is that private use still isn’t deductible. Weekend trips to the tip, school drop-offs and camping at Noosa are private. You need records showing how you work out your business percentage, and a logbook is still the easiest way to prove it.

If you’re operating through a company and the ute is available for private use, fringe benefits tax can come into play too. There is an exemption for work vehicles where private use is minor, but “minor” has a specific meaning. Ask before you assume.

Travel: the one everyone gets wrong

Driving from home to your regular workplace is private travel. Not deductible. Even if you’re a tradie.

What you can claim:

  • travel between job sites during the day
  • trips to the supplier to pick up materials
  • home to site travel if you genuinely need to carry bulky tools or equipment (think ladders, generators, a trailer full of gear) and there’s no secure place to store them on site
  • travel where your home is your base of operations and you’re heading out to clients

“I had my phone and a hammer in the ute” doesn’t count as bulky tools. The ATO has seen that one before.

Tradie tax deductions for clothing and PPE

You can claim:

  • steel cap boots, hi-vis and other protective gear
  • branded uniforms with your business logo
  • sunscreen, sunglasses and hats if you work outdoors
  • the cost of laundering protective or branded clothing

You can’t claim plain work shorts, jeans, black T-shirts or the hoodie you also wear to the footy. If you could wear it out on a Saturday, it’s private.

Phone, internet and admin

Your phone is probably your office. You can claim the business portion of your phone and data, but you need to work out a fair percentage. A four-week diary of your typical usage is the standard way to back it up.

Other admin deductions tradies often forget:

  • accounting and bookkeeping software (Xero, MYOB, job management apps)
  • licence renewals, such as your QBCC licence renewal (the very first licence isn’t deductible)
  • union fees and industry association memberships
  • training that maintains or improves skills in your current trade
  • tax agent fees from last year

Records that back up your tradie tax deductions

The ATO doesn’t care what you spent. It cares what you can prove. Keep:

  • receipts or invoices for everything (a photo in your bookkeeping app is fine)
  • a logbook for your vehicle
  • a usage diary for your phone
  • bank statements that match your claims

If your receipts live in the console of the ute until June, you’re leaving money on the table and creating risk at the same time. Getting your bookkeeping sorted weekly beats a shoebox scramble every time.

The honest bit

Tradies work hard for their money, and you should claim every dollar you’re entitled to. You just shouldn’t claim the ones you’re not. Getting your tradie tax deductions right is usually a bit of planning and decent records, not a clever trick.

We look after trades businesses across Brisbane and we’ll tell you straight what you can claim, what you can’t, and how to set things up so tax time isn’t a horror show. Book a time with us and we’ll take a look.

Related reading:

This article is general information only and isn’t personal advice. Your situation may be different, so please get advice before acting.
Advice Business Tax

Allied Health Payroll Tax in Queensland: Why the GP Exemption Doesn’t Cover You

If you own an allied health practice in Queensland, you probably cheered when the State Government exempted GP practices from payroll tax. Here’s the bit nobody put in the headlines: that exemption is for GPs only. Physios, psychologists, OTs, podiatrists, dietitians, speechies and chiros are not covered.

So if your practice pays contractors and your total wages bill is creeping up, allied health payroll tax in Queensland is something you need to understand now, not when the Queensland Revenue Office (QRO) sends a letter.

What actually changed for medical practices

Queensland passed legislation in February 2025 making payments by medical practices to general practitioners exempt from payroll tax and the mental health levy, backdated to 1 December 2024. Before that, an amnesty covered contracted GP payments from 1 July 2018.

The amnesty specifically excluded “other medical doctors or allied health professionals.” The permanent exemption is written around GPs too. If your clinicians aren’t GPs, the old rules still apply to you in full.

Allied health payroll tax basics in Queensland (2026-27)

  • Threshold: $1.3 million a year in Australian taxable wages (about $108,333 a month)
  • Rate: 4.75% if your Australian wages are $6.5 million or less, 4.95% above that
  • Deduction taper: the $1.3 million deduction reduces by $1 for every $7 of wages above it
  • Mental health levy: applies on top for employers with wages over $10 million

The 2026-27 Queensland Budget made no changes to these rates or thresholds.

“Wages” is broader than most practice owners think. It includes salaries, super, bonuses, allowances, fringe benefits and, importantly, some payments to contractors.

How contractor payments become “wages”

Queensland, like the other states, has “relevant contract” rules. If your practice pays someone to perform work, that payment can be treated as wages for payroll tax even if the person has an ABN, sends you invoices and calls themselves a contractor.

This is exactly how medical centres got caught. Revenue offices and tribunals looked at arrangements where the practice collected patient fees, took a service fee and paid the rest to the practitioner. The finding was that the practice was effectively paying the practitioner to provide services to the practice’s patients. That’s a relevant contract.

Plenty of allied health clinics run the same model. If that sounds like yours, keep reading.

The exemptions (and why they’re narrower than you hope)

There are exemptions designed to carve out genuine independent contractors. Broadly, a payment may be exempt where:

  • the contractor ordinarily provides those services to the public generally in that financial year, not just to your practice
  • the services are performed for 90 days or less in a financial year
  • the services are of a kind you ordinarily require for less than 180 days a year
  • the Commissioner has made a determination for that arrangement

The catch is that QRO looks at what actually happens, not what your contract says. A physio who works four days a week in your rooms, using your reception, your booking system, your branding and your patient list, is going to have a hard time arguing they serve “the public generally” independent of you.

The grouping trap

Lots of practice owners think they’re well under $1.3 million. Then they find out about grouping.

If you own more than one business (say, a service company, a property trust and the clinic itself, or two clinic locations in separate entities), QRO can group them. Wages are added together and only one threshold is shared across the group. Two clinics on $800,000 each look fine on their own. Grouped, you’re $300,000 over.

Allied health payroll tax in real numbers

Say your Brisbane allied health practice pays $1.8 million a year across employed admin staff and contracted clinicians, and the contractor payments don’t fit an exemption.

  • Your deduction drops to about $1,228,571 (that’s $1.3 million less one seventh of the $500,000 above it)
  • Taxable wages are around $571,429
  • Payroll tax at 4.75% is roughly $27,100 a year

Now picture QRO reviewing five years at once, plus interest and penalty tax. That’s the scenario the GP practices were in, and why they lobbied so hard.

Allied health payroll tax: what to do now

You don’t need to panic. You do need to look. Here’s where we’d start:

  1. Add up your Australian wages properly. Include super, contractor payments and every entity you or your family control.
  2. Map how money flows. Who collects patient fees? Who sets prices? Whose name is on the receipt? This matters more than the contract title.
  3. Test each contractor against the exemptions. Do they genuinely work elsewhere? How many days a year are they in your rooms?
  4. Review your service agreements. Older templates written for GP clinics may not hold up for allied health.
  5. Get advice before you restructure. Some fixes create new problems with GST, super or Medicare billing.

If you’re already over the threshold and haven’t registered, a voluntary disclosure to QRO usually lands better than waiting for them to find you.

The honest bit

Most allied health owners didn’t set up their practice expecting an allied health payroll tax bill. Nobody told them. But “nobody told me” isn’t a defence QRO accepts, and the GP exemption has made it easy to assume the whole health sector got a pass. It didn’t.

We work with allied health practices across Brisbane and Queensland, and we’ll tell you where you actually stand, not what you’d like to hear. If you want a straight answer on your payroll tax exposure, book a chat with us.

You might also find these useful:

This article is general information only and isn’t personal advice. Payroll tax outcomes depend on your specific arrangements, so please get advice before acting.